Amazon strategy · 11 minute read
How to sell an Amazon business: what buyers pay for, and how to raise the price
A buyer pays a multiple of your profit, not your sales. That one fact decides how to prepare, what to fix first and how to read every offer. Here is how valuation works today, what the published numbers say, and the process from first call to handover.
By Robert Prime, CEO and co-founder
Reviewed by Atouka Tsochataridis, Growth Director
- Published
- Last reviewed
- Sources
- 12 primary and labelled
Cover designed for Mr. Prime.
The short answer
Key takeaways
- Buyers price an owner-run Amazon business as a multiple of yearly profit: SDE for most smaller businesses, EBITDA for larger ones with a management team.
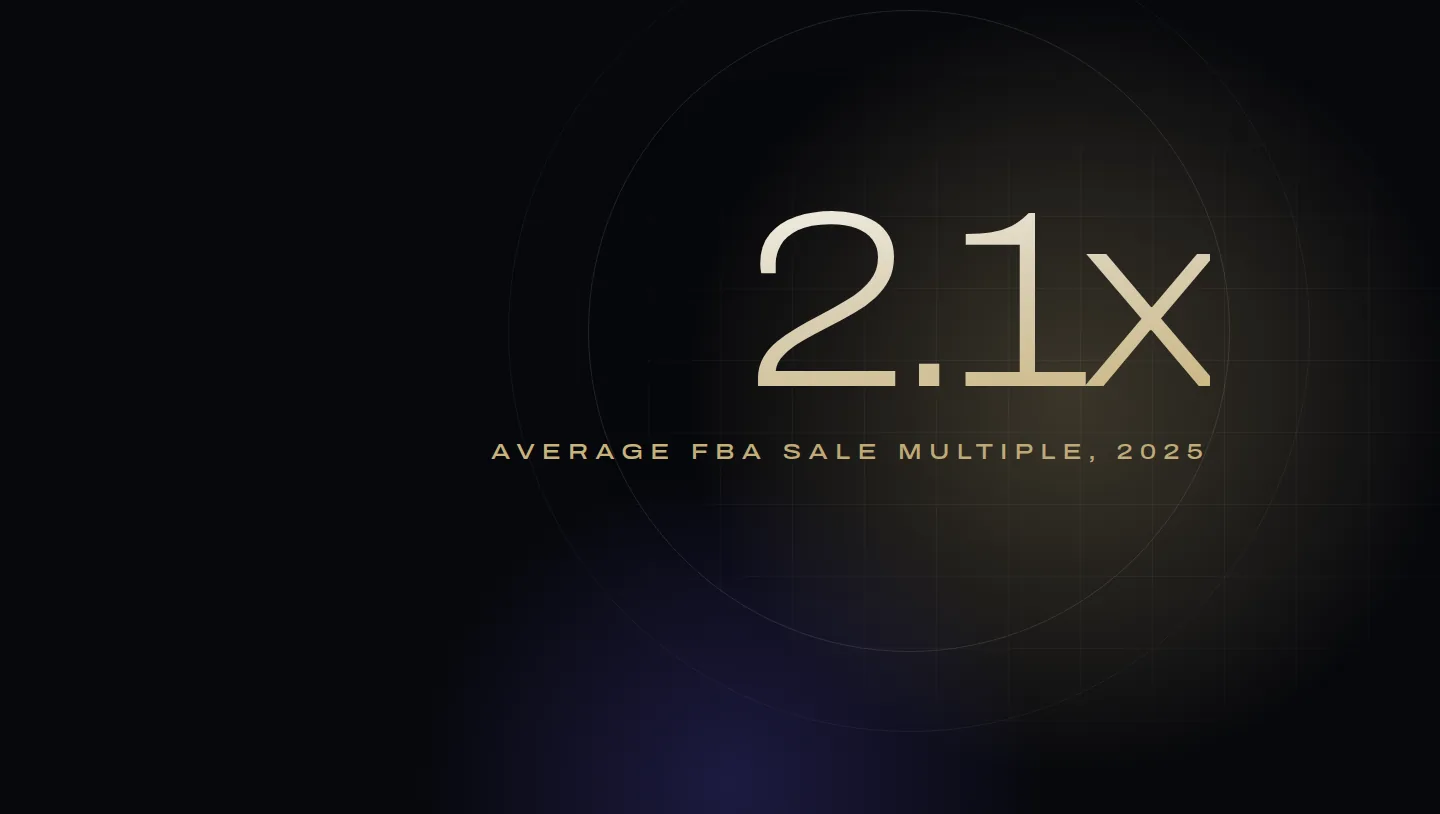
- Published figures are well below the aggregator boom: Empire Flippers’ 62 Amazon FBA sales in 2025 averaged 2.1×, Flippa’s 2025 ecommerce deals 1.4× (2.7× top quartile), and FE International cites 2–4× SDE for smaller ecommerce businesses.
- The multiple rises with age, stable growth, several products, sales beyond Amazon, a registered trade mark and a business that runs without you. It falls with one-product, one-channel, founder-dependent businesses.
- Amazon’s Business Solutions Agreement can’t be assigned without Amazon’s written consent, so plan early how the seller account, Brand Registry and trade marks will pass to the buyer.
- Every £1 of profit is multiplied. In our illustration, cutting 2 points of wasted ad spend and de-risking the business lifts the price from £450,000 to £612,000.
By the numbers
- 2.1×
- Average multiple of the 62 Amazon FBA businesses Empire Flippers sold in 2025
- 2–4×
- SDE multiples FE International cites for smaller ecommerce businesses (April 2026)
- 60–75%
- Share of the price typically paid upfront in aggregator deals, the rest in earn-outs over 12 to 24 months (FE International)
- +£162,000
- Price gained from 2 points of margin and a lower-risk business, at £1.2m of sales (illustration)
From Robert Prime, who has built and sold an Amazon brand, and the Mr. Prime team, who manage Amazon accounts for founder-led UK brands with the profit after advertising that a buyer will multiply.
Most founders find out what their Amazon business is worth the hard way: a buyer or broker tells them, and the number is a multiple of a profit figure they have never calculated. It is rarely a multiple of sales, and it is rarely the number they had in mind.
This guide works from the buyer’s side of the table. It covers how buyers value an owner-run Amazon business, what the latest published multiples say, what raises and lowers your multiple, the sale process, how the seller account, Brand Registry and trade marks change hands, and what happened to the aggregators. It is the end of the journey our guide to selling on Amazon in the UK begins, and the reason every guide on this site is judged on net profit. To put your own figures in, use our Amazon business valuation calculator.
How buyers value an Amazon business
SDE or EBITDA
Almost every buyer starts with the same equation: price = yearly earnings × multiple. The argument is about which earnings and which multiple.
| Seller’s discretionary earnings (SDE) | EBITDA | |
|---|---|---|
| What it is | Profit available to one owner-operator | Earnings before interest, tax, depreciation and amortisation |
| How it’s built | Revenue − cost of goods − operating expenses + the owner’s salary1 | Owner and management pay treated as normal costs |
| Used for | Most smaller, owner-run businesses: Empire Flippers says businesses valued at $5m or less on its marketplace1; FE International says businesses valued under $10m3 | Larger businesses with a team in place13 |
| Typical buyer | An individual operator or a small fund | Private equity, strategic buyers, surviving aggregators |
The earnings are normally the last 12 months. Empire Flippers calls the 12-month window “the gold standard”; a six-month window is used when a business has changed recently or is young, and it “will result in a lower multiple and less buyer interest"1.
Add-backs
SDE adds back costs a new owner won’t carry. The usual ones are your own salary, genuinely one-off costs (a rebrand, a legal dispute, a failed product written off) and personal costs run through the company. Every add-back has to survive due diligence, so keep the invoice and a one-line note of why it won’t recur. In our experience, add-backs a buyer can’t verify are simply deducted again, and they cost you credibility on the rest of the numbers.
Advertising is not an add-back. A buyer will look hard at it, though, because ad spend above break-even is profit you could have reported. Our TACoS benchmarks guide shows what buyers will compare yours against.
What multiples look like now
Only use multiples from named, dated sources, and read the small print on each. These are the most recent published figures we could verify:
| Source and date | What it covers | Multiple |
|---|---|---|
| Empire Flippers, page updated 8 September 2026 | 62 Amazon FBA businesses sold on its marketplace in 2025, average price $283,000 | Average **2.1×**1 |
| Flippa, 19 December 2025 | Ecommerce businesses sold on its marketplace, January to December 2025 | Average 1.4×; top quartile **2.7×**2 |
| FE International, 27 April 2026 | Ecommerce M&A generally | 2–4× SDE for smaller businesses; 3–6× EBITDA for the typical business; 2.5–5× for smaller DTC brands; 7× or more for larger, professionally managed ones3 |
| FE International, 27 April 2026 | Aggregator acquisitions | Down from 6–7× EBITDA at the peak to 3–4× for most categories3 |
Four cautions before you use any of these:
- They are averages. Empire Flippers says plainly that no single multiple applies to every Amazon FBA business1.
- They are mostly small, US, dollar deals. Flippa’s average is dragged down by very small listings; FE International’s figures cover larger deals.
- The earnings bases differ. Empire Flippers multiplies net profit, usually over 12 months1; FE International uses SDE or EBITDA by size3. A 3× EBITDA and a 3× SDE are not the same price.
- Structure changes the real price. An offer at 3× with a third paid in an earn-out you may not hit can be worth less than 2.5× in cash.
What raises the multiple, and what lowers it
Buyers price risk. Empire Flippers lists the factors it weighs, and calls business age “the most important factor considered when determining a multiple"1. FE International adds that the strongest candidates in 2026 sell across several channels, and that brand equity separates “a 3x and a 5x+ multiple"3.
| Raises the multiple | Lowers the multiple |
|---|---|
| Several years of stable or growing earnings1 | A short history, or a recent spike or drop1 |
| Profit spread across several products1 | One hero product carrying the business |
| Sales on other channels as well as Amazon3 | Amazon as the only channel |
| A registered trade mark and Brand Registry1 | No trade mark, or one held personally or by a supplier |
| More than one reliable supplier1 | A single supplier, no written terms |
| A team and documented processes; low owner hours1 | A founder who runs advertising, buying and service personally |
| Strong reviews, an email list and social audience1 | A weak or falling rating |
| Clean account health and steady stock | Stock-outs, suppressed listings or policy warnings |
Channel concentration and founder dependency are the two we see cost UK sellers most. A buyer who sees 100% of sales from one Amazon account, run day to day by the founder, is buying two risks at once, and prices both.
Robert’s view: Having built and sold an Amazon brand myself, the lesson I would pass on is that the work that raises the price is the same work that makes the business better to own. Start it a year before you want to sell, not when the buyer’s questions arrive.
Every £1 of profit is worth a multiple
What a buyer pays
Sale price = SDE (or EBITDA) × multiple
Add-backs must be documented. Stock is sometimes priced on top of the multiple, so agree how it is treated in the letter of intent.
Two points of margin and a less founder-dependent business add £162,000 to the price. That is why we judge every Amazon decision on profit after advertising: at exit, each extra £1 of yearly profit is worth £2 to £3 or more. The same logic is behind the exit value in our agency ROI calculator, and our valuation calculator shows what each lever is worth on your own figures.
The sale process
Selling an Amazon business, from preparation to handover
- Prepare the numbersTwelve months or more of monthly profit and loss, reconciled to Seller Central payments reports, with every add-back documented. Fix account health issues and stock gaps first.
- Get a valuation and choose how to sellA specialist broker or adviser markets the business to many buyers and runs the process; selling direct to one buyer is faster but rarely tests the price.
- Market under NDAA teaser, then a full information pack for buyers who sign a non-disclosure agreement. Expect calls about how the business runs and how much time you spend on it.
- Agree a letter of intentThe price, how much is paid upfront and how much later, inventory treatment, any earn-out targets, the handover period and an exclusivity window.
- Due diligenceThe buyer checks the accounts against Amazon’s reports, account health, trade marks, supplier terms, stock, reviews and advertising. Most deals that fail, fail here.
- Sign and completeA share or asset purchase agreement, then payment, transfer of accounts, trade marks and supplier relationships.
- Hand overA transition period of training and support, and earn-out reporting if part of the price depends on future results.
On structure, FE International reports that in aggregator deals the upfront cash now averages 60–75% of the total, with the rest tied to earn-outs over 12 to 24 months3. An earn-out shares the risk of the business after you leave it. Read its targets as carefully as the headline price, and ask who controls the levers, such as advertising budgets and stock, that decide whether you hit them.
Transferring Seller Central, Brand Registry and trade marks
The seller account. Amazon’s Business Solutions Agreement for Europe says: “You may not assign this Agreement, by operation of law or otherwise, without our prior written consent.” The exception is assignment to your own affiliates, on notice to Amazon4. In practice that is why many buyers of UK Amazon businesses buy the company that holds the account, so the account stays with the same legal entity under new owners, rather than buying its assets into a different company. Which route suits your deal is a question for your lawyer and accountant; settle it before the letter of intent, because it changes the tax and the paperwork. Either way, expect the new owners to update the account’s business and contact details, and keep the account healthy throughout the handover.
Brand Registry. Brand Registry has protection roles: an Administrator, who can assign roles to users, and a Rights Owner, the trade mark owner or their employee, who can use Report a Violation and the brand protection tools5. Amazon’s staff advise that the current brand owner adds the new owner as Administrator and Rights Owner, after which the former owner can be removed6. Do it in that order, and only once the trade mark has changed hands.
Trade marks. A UK trade mark is transferred by assignment, recorded with the Intellectual Property Office on form TM16, which costs £607. If the mark is held in your personal name rather than the company’s, fix that well before a sale; a buyer of the company will otherwise find the brand’s most valuable asset is not in it. Our Brand Registry guide covers registration.
Tax. For a UK seller, Business Asset Disposal Relief can reduce the Capital Gains Tax rate to 14% on qualifying disposals between 6 April 2025 and 5 April 2026, and 18% from 6 April 2026, subject to conditions such as holding at least 5% of the shares and voting rights of a trading company and being an officer or employee for at least two years8. Take advice early; the conditions are tested over the two years before the sale.
The aggregator landscape since 2022
Between 2020 and 2022, aggregators raised capital to buy Amazon brands in bulk. Marketplace Pulse’s tracker puts the total raised at more than $16bn, with Thrasio alone at $3.4bn12. Funding then fell away: citing CB Insights, Practical Ecommerce reported that global funding to Amazon aggregators peaked at just over $6bn in 2021 and fell 88% in 202211.
What followed was consolidation and repair:
- Mergers. In May 2023 SellerX agreed to buy Elevate Brands, and two smaller US aggregators, Suma and D1 Brands, merged11. In March 2024 Razor Group acquired Perch, which it described as the leading US Amazon aggregator, following its earlier purchases of Factory14, Valoreo and The Stryze Group10.
- Restructuring. On 28 February 2024 Thrasio filed for Chapter 11 bankruptcy protection, with $90m of new financing from existing shareholders and a deal with lenders to cut $495m from its debt9.
- Lower prices, more structure. FE International describes the survivors as having learned that “acquiring brands at 6-7x EBITDA only works if you can actually operate them profitably post-acquisition”, with valuations now at 3–4× for most categories and more of the price in earn-outs3.
For a seller, the lesson is that the buyer pool is now broader and more careful: individual operators, small funds, private equity, strategic buyers and the remaining aggregators. Empire Flippers says its 2025 multiples are back “much closer to what we were seeing in 2019 before the boom took off"1. Plan on today’s numbers, not 2021’s.
What to do in the year before you sell
- Measure profit the way a buyer will. Monthly, product by product, after advertising, reconciled to Amazon’s payment reports. The Profit X-Ray is a quick start.
- Take out spend that doesn’t pay. Advertising above break-even, slow stock paying storage fees, products that lose money. Every £1 recovered is multiplied.
- Reduce concentration. A second hero product, a second channel, a second supplier.
- Make yourself optional. Document advertising, buying and customer service, and have someone else run them for at least a few months before the sale.
- Put the intellectual property in order. Trade marks in the company’s name, Brand Registry roles clean, no listings depending on someone else’s brand.
- Keep the business growing while you sell. A dip during due diligence costs more than the effort of holding steady.
Robert’s view: The businesses that sell well are run as if they are always for sale, with the numbers ready, the risks named and the owner able to step back. If you build it that way, you may decide not to sell at all, and that is a good position to negotiate from.
Frequently asked questions
How much is my Amazon business worth?
What is SDE?
Can I transfer my Amazon seller account to a buyer?
Do Amazon aggregators still buy brands?
How long does it take to sell an Amazon business?
Do I pay tax when I sell my Amazon business?
Sources
- How to value an Amazon FBA business: with real sales data. Empire Flippers, updated 8 September 2026. Checked 1 October 2026.
- Online business M&A insights: 2025 recap and 2026 outlook. Flippa, 19 December 2025. Checked 1 October 2026.
- The state of ecommerce M&A in 2026: DTC brands, Amazon aggregators and what buyers want now. FE International (Thomas Smale), 27 April 2026. Checked 1 October 2026.
- Amazon Services Europe Business Solutions Agreement (assignment clause). Amazon Seller Central UK, last updated 30 June 2025. Checked 1 October 2026.
- Brand Registry selling and protection roles. Amazon Seller Forums (Amazon staff post). Checked 1 October 2026.
- Brand registry ownership transfer (Amazon staff reply). Amazon Seller Forums. Checked 1 October 2026.
- Trade mark forms and fees (TM16: application to record a change of ownership). Intellectual Property Office, GOV.UK. Checked 1 October 2026.
- Business Asset Disposal Relief. GOV.UK. Checked 1 October 2026.
- Amazon aggregator Thrasio files for bankruptcy. Reuters, 28 February 2024. Checked 1 October 2026.
- Razor Group acquires US Amazon aggregator Perch and announces Series D financing round. Razor Group via PR Newswire, 5 March 2024. Checked 1 October 2026.
- Amazon aggregators face a new reality. Practical Ecommerce, 19 June 2023. Checked 1 October 2026.
- Amazon aggregators (tracker of capital raised and deals). Marketplace Pulse. Checked 1 October 2026.
How this guide was made
Written by Robert Prime, who has built and sold an Amazon brand, and reviewed by Atouka Tsochataridis, Head of Growth at Mr. Prime. We used AI tools to help research and draft it; Robert edited it and takes responsibility for it. Valuation multiples come only from the named, dated broker and marketplace reports listed above, checked on 1 October 2026; they are averages from mostly US, dollar-denominated deals and are not a valuation of any business. Amazon, UK IPO and HMRC rules were checked against their primary pages on the same date. This guide is not legal, tax or financial advice.
Every figure above links to the primary source it came from, and we recheck them when Amazon changes its fees or definitions. Read our editorial standards. Spotted something wrong? Tell us through our contact page and we will correct it and note the change here.
About the author
Robert Prime
Robert has spent more than two decades building, growing and selling online businesses, including an Amazon brand he built and sold for seven figures.
His other exits include Telematics.com, sold to LexisNexis, and Remortgage.com. He co-owned UpDownDesk.com.au, growing it on Shopify alone from £12k to £350k a month before he exited, one of more than six Shopify businesses he has built and sold.
He sets and reviews the strategy for every Mr. Prime client, with the view of an operator who has sat on your side of the table.
Reviewed by
Atouka Tsochataridis
A former soldier who overdelivers every time. Runs growth across the client book and is on WhatsApp with clients at all hours.
Your numbers, not ours
See your own break-even, TACoS and profit after ads.
The Profit X-Ray works it out from four monthly figures, or from your Business Report, in your browser.